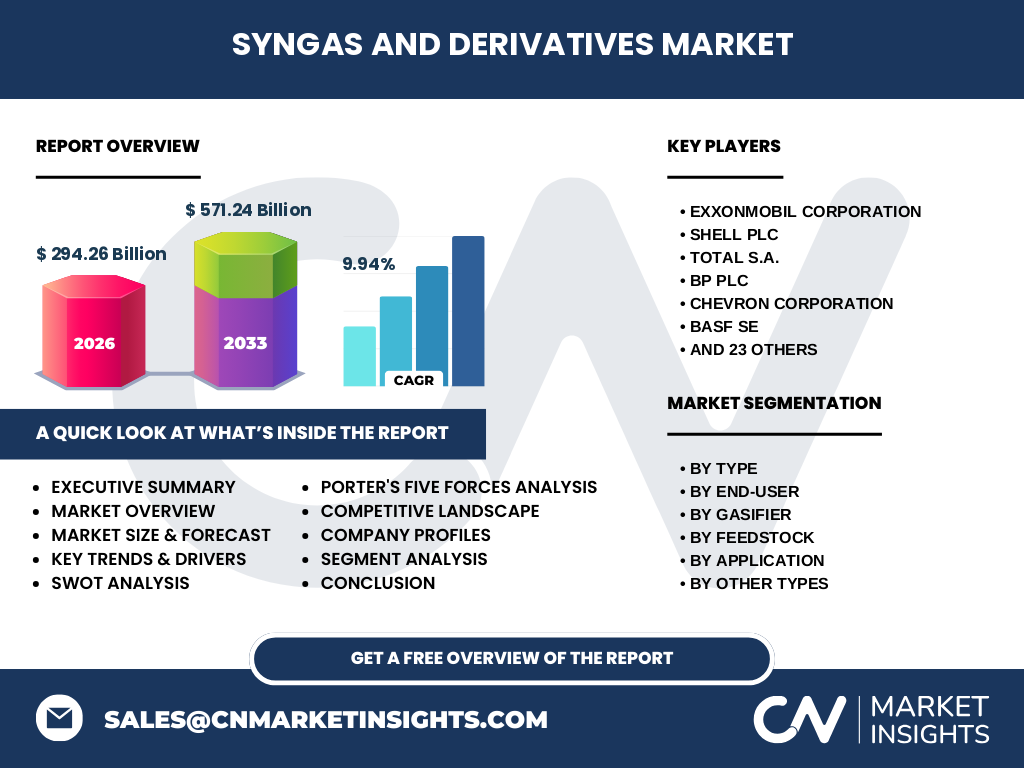
Market overview of the Syngas And Derivatives Market
The global Syngas And Derivatives Market size reaches $294.26 Billion in 2026, serving as the foundational chemical backbone for industrial synthesis. Our research indicates that synthesis gas conversion drives global manufacturing of ammonia, methanol, and synthetic hydrocarbons across major processing hubs.
Key market drivers, restraints, challenges, and opportunities shaping the industry
Growth accelerates due to rising chemical feedstock demand, though volatile carbon pricing acts as a key market restraint. Environmental compliance mandates challenge traditional coal gasification plants, while green hydrogen integration presents lucrative expansion opportunities for forward-thinking refiners.
Emerging trends and growth patterns in Syngas And Derivatives Market
Decarbonization dominates current industry trends, with operators shifting toward biomass and municipal waste gasification. Companies like Synhelion SA pioneer solar thermochemical pathways, altering traditional carbon-heavy production models and redefining long-term commercial growth patterns.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions temporarily halted capital expenditures across petrochemical complexes globally. Based on our analysis, strategic stimulus packages and rebounding chemical demand accelerated the recovery trajectory, pushing output past pre-health-crisis baselines.
Competitive landscape and strategic market concentration
The market features high capital concentration among engineering giants and energy majors. Shell PLC, Air Liquide SA, and Linde PLC dominate intellectual property portfolios, leveraging proprietary gasification technologies to secure long-term industrial gas supply contracts.
Executive summary of key findings
Our comprehensive analysis values the industry at $294.26 Billion for 2026, scaling rapidly toward $571.24 Billion by 2033. This expansion reflects a robust 9.94% CAGR, driven by industrial upgrading and strict environmental mandates.
Market forecast from 2027 to 2033
The market is projected to expand from $294.26 Billion in 2026 to $571.24 Billion by 2033, achieving a steady 9.94% CAGR. Clean energy transitions and heightened demand for downstream derivatives anchor this exceptional medium-term forecast.
Segmentation analysis across types, end-users, gasifiers, feedstocks, and applications
Segmentation spans By Type (Partial Oxidation, Steam Reforming, Biomass Gasification), By Feedstock (Coal, Natural Gas, Petroleum, Biomass Or Waste), By Gasifier (Fixed Bed, Entrained Flow, Fluidized Bed), By End-User (Industrial, Residential, Commercial), and By Application (Chemicals, Power Generation, Liquid Fuels).
Regional market analysis and geographic performance
Asia-Pacific dominates consumption patterns due to extensive coal gasification infrastructure in emerging industrial zones. North America and Europe follow closely, prioritizing technological upgrades, carbon capture integration, and stricter environmental compliance frameworks.
In-depth regional review of key markets
In Asia-Pacific, massive chemical complexes drive natural gas and coal gasification demand. Meanwhile, European markets enforce stringent emissions standards, forcing operators in Rotterdam and Antwerp hubs to accelerate green hydrogen and circular waste gasification projects.
Company profiles and strategic positioning of leading players
Industry leaders maintain distinct competitive moats through proprietary technology licensing. Topsoe A/S and KBR Inc. provide essential catalysis and engineering services, while Sasol Ltd. specializes in advanced Fischer-Tropsch liquid fuel synthesis from coal and gas.
Porter's Five Forces analysis of competitive intensity
High capital expenditure requirements create a formidable barrier to new entrants, while buyer power remains moderate due to specialized gas supply agreements. Supplier power fluctuates with feedstock commodity pricing, particularly for natural gas and metallurgical coal inputs.
SWOT analysis of the global sector
Strengths lie in established technological infrastructure and diverse derivative applications. Weaknesses include high greenhouse gas emissions. Opportunities emerge in circular waste utilization, whereas regulatory threats from carbon taxation challenge traditional fossil-based assets.
Value chain analysis from raw materials to end-users
The value chain originates with raw material extraction—primarily coal, natural gas, and biomass—feeding into specialized gasifier units. Midstream purification yields synthesis gas, which downstream processors convert into value-added chemicals, synthetic fuels, and hydrogen products.
Investment insights and strategic recommendations
Investors should target technology providers specializing in plasma gasification and autothermal reforming to capture decarbonization upside. Prioritizing assets aligned with circular bio-feedstocks mitigates future regulatory risk and secures long-term margins.
Conclusion and key takeaways for stakeholders
Reaching $571.24 Billion by 2033 at a 9.94% CAGR underscores the sector's vital economic role. Stakeholders must pivot toward sustainable feedstocks and advanced carbon abatement technologies to maintain competitiveness.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from international energy agencies to ensure maximum analytical accuracy.
Scope of the report and coverage parameters
This report evaluates global market dynamics, regional performance metrics, and technological segmentations across the 2026 to 2033 timeline. Limitations exclude localized informal micro-gasification units operating outside recognized industrial reporting standards.
Recent developments in the industry
Recent strategic moves feature major engineering partnerships focused on net-zero chemical production. Firms like Air Products and Chemicals Inc. have announced large-scale green hydrogen and syngas ventures to align with aggressive global decarbonization targets.